/11 min read
An AI research report priced SMDR's fair value using a share count that was off by 109 times. I rebuilt the case from the actual filings, and the reason turned out to be cash, not the fastest growth.
Two weeks ago I wrote about how the $150 oil number gets built, and about ton-miles, the measure of how much ship capacity is actually available at any given time. The question that followed: if that logic holds, which Indonesian shipping stock is worth a closer look?
I already hold SMDR, PT Samudera Indonesia Tbk, from before I started putting this together. What follows is a record of my own reasoning, not an invitation to buy. I could be wrong, and part of this post is about exactly where I think I’m most likely to be.
Before any of that, I should explain why this post took longer than usual. My first pass at the research was AI-assisted, and it priced SMDR’s fair value by dividing an equity estimate by “150 million shares.” SMDR actually has 16,375,600,000 shares, following a 1:5 stock split on 31 January 2023. That’s off by a factor of 109. With the wrong share count, the report produced a fair value of Rp132,000 to Rp212,000, when the actual price at the time was Rp394. Not just off, but impossible: at the real share count, that valuation would make SMDR worth more than any company on the Indonesia Stock Exchange.
So I threw the whole calculation out and started again from the company’s own filings.
Three ships, three different businesses
Three names keep coming up together when people talk about Indonesian shipping stocks, and each one is actually selling something different.
SMDR is diversified. Consolidated revenue was US$801.69m in 2025, but broken out by segment the figures run higher: shipping and agency US$640.27m, logistics and ports US$170.24m, the rest US$27.83m. The three segments add up to US$838.34m, about US$36.7m above consolidated revenue, a gap that usually comes from eliminating transactions between segments. I’m stating the figures as reported rather than claiming I’ve reconciled that gap myself. A subsidiary holds a stake in PT Patimban Global Gateway Terminal, and its container fleet runs through Samudera Shipping Line, which is separately listed on the Singapore exchange.
BULL, by contrast, is close to pure tanker. Freight revenue was US$126.32m of total operating revenue of US$128.73m in 1H2026, about 98 percent. If tanker rates rise, almost all of its revenue rises with them.
SOCI sits between the two. Alongside operating its own tankers, it owns a shipyard subsidiary, PT Multi Ocean Shipyard (MOS), which builds and repairs vessels from tankers to tugs and AHTS boats.
All three get called “shipping stocks,” but comparing them as if they’re betting on the same thing is wrong from the start.
Why tanker and LNG rates are running this high isn’t a mystery to me. The Panama Canal is rationing transits because of drought, and the Strait of Hormuz has been effectively shut since the war began in late February 2026, while Bab el-Mandeb keeps heating up under the Houthi blockade. All three force ships to take longer routes, which stretches voyage time and shrinks the world fleet’s effective capacity for the same cargo. That’s the ton-mile logic from my last two posts. I don’t have a figure that directly ties those three disruptions to BULL’s TCE, but my guess is they’re a large part of why its tanker and LNG rates sit where they do right now. SMDR feels the same pressure through its container and bulk side, just far more slowly, because that isn’t the only thing driving its revenue.
The fastest grower isn’t the one I picked
Looking only at how fast first-half 2026 profit grew, SMDR isn’t the winner. Not close.
BULL posted a profit of US$58.41m in 1H2026, up 739 percent from US$6.96m a year earlier. The driver was its tanker segment’s time charter equivalent rate, which Bisnis.com reports rose from US$40,007 a day in October 2025 to US$62,987 a day in December 2025. Its LNG segment jumped even harder, from US$12,667 to US$65,167 a day over the same stretch, though that’s a different segment’s number and shouldn’t be blended with the tanker figure.
SOCI rose 190 percent, from US$6.996m to US$20.29m, on gross profit that grew 22 percent.
SMDR rose 11.0 percent, from US$29.30m to US$32.52m. Solid, but if I’m honest, it’s the least impressive of the three.
If my reason for holding SMDR were growth speed, I’d have picked the wrong stock. My reason sits somewhere else.
Cash that very nearly matches its market cap
This is the part that made me stop and do the arithmetic myself.
ANTARA reported SMDR’s total assets at US$1.48 billion for 1H2026. From that same interim report, as of 30 June 2026, its cash and cash equivalents were US$370,104,520, a figure I read directly from the financial statement itself. Its market cap, using the 18 September 2026 closing price of Rp394 and 16,375,600,000 shares outstanding, comes to around Rp6.45 trillion. Converted at that day’s JISDOR rate, that’s roughly US$363.6 million.
394 × 16,375,600,000 = Rp6,451,986,400,000
Rp6,451,986,400,000 / 17,745 = US$363.6 million
Which means SMDR’s cash alone, just the cash, very nearly equals the entire price the market is paying for the company. Not convincingly more, just about 2 percent less, and a margin that thin could flip either way with a small shift in the exchange rate or in cash between the end of June and the day I did this math. But whichever way it leans, the gap is thin enough to make one thing clear: the market is pricing the entire fleet, ports and contracts at close to nothing, on top of the cash.
That doesn’t mean SMDR is debt-free. Total debt is US$528.0m, more than its cash; the difference, my own subtraction, puts net debt at around US$157.9m. But most of that figure isn’t ordinary bank borrowing. From the same interim filing, lease liabilities for chartered-in vessels come to about US$225m, plus long-term loans of US$175.3m and Sukuk Ijarah of US$85.6m. Lease liabilities are simply the accounting entry for ships taken on charter.
BULL and SOCI don’t have the same luxury. BULL’s market cap of roughly US$340.4m sits against cash of just US$18.9m. SOCI’s gap is thinner still: a market cap of US$256.6m against cash of about US$9.0m.
BULL’s and SOCI’s total assets haven’t come up yet. BULL reported total assets of US$461.34m as of 30 June 2026 in the same audited filing as its working-capital figure, and SOCI reported US$651.22m on the same date, in the same article as its net profit figure.
Put together in one table, the four figures I’ve been citing separately:
| Metric (1H2026) | SMDR | BULL | SOCI |
|---|---|---|---|
| Net profit growth | +11.0% | +739% | +190% |
| Cash | $370.1m | $18.9m | $9.0m |
| Total assets | $1,482.0m | $461.3m | $651.2m |
| Working capital | positive | −$6.75m | −$25.6m |
The first row says BULL and SOCI win. The second and third rows say why I still hold the one in the first column: SMDR’s assets are more than three times BULL’s, and it’s the only one of the three whose working capital is still positive.
Two more fragile balance sheets
This part I have to get right, because the report I threw out at the start of this post misquoted it too, and the corrected version still matters.
BULL’s audited statements as of 30 June 2026 show current liabilities exceeding current assets by about US$6.75m, and an accumulated deficit of US$158,163,265. I read both figures myself from the filing and they match exactly. What doesn’t match is the claim that the auditor’s report contains a “material uncertainty related to going concern” paragraph. What’s actually there is a qualified opinion over receivables under reconciliation, in Note 7, while the statements themselves are prepared on a going-concern basis with management’s plan set out in Note 36. Those are different things, and I’m not going to use language the report itself doesn’t use.
BULL’s fleet claim needs the same correction. The company’s own page says its fleet grew from 8 vessels in 2013 to 32 vessels with 2.4 million DWT of capacity.
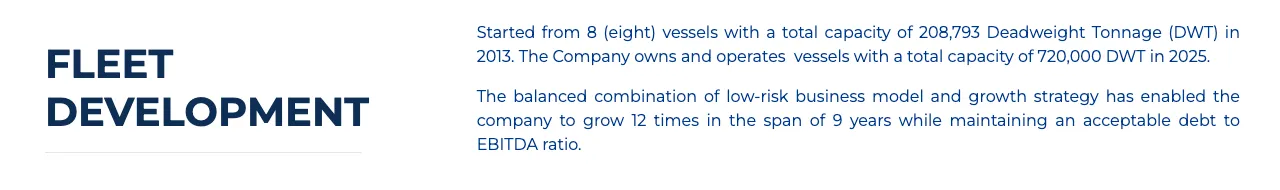
BULL’s Fleet Development page, captured 19 September 2026. The first sentence gives 720,000 DWT for 2025; the second claims 12-fold growth from 208,793 DWT, which points back to the 2.4 million figure on the same page.
Two sentences on their own official page don’t agree with each other. BULL’s 2025 Sustainability Report goes with the smaller, more specific figure: 9 vessels, 643,000 DWT for that year. I’ve used that one, and named the conflict, rather than quietly picking whichever suited the story.
SOCI also carries debt, and the report I discarded got the size of it wrong too. Its claim of “US$175.84m from Mandiri and BCA” turns out to be roughly the size of the syndicated facility when it was first arranged in December 2020, around Rp2.54 trillion. The balance still outstanding as of 31 March 2026 was about US$87.58m, Mandiri’s US$65.69m plus BCA’s US$21.89m, roughly half. SOCI is even issuing part of a sukuk ijarah specifically to pay down what’s left of it.
SOCI’s working capital is negative too, and worse than BULL’s: current assets sit US$25.6m below current liabilities, against BULL’s US$6.75m shortfall.
Where I still have doubts
If I’m honest about where I could be wrong, here’s the list.
SMDR really is the slowest grower of the three, and the diversification that shields it from the tanker cycle currently running hot also means it doesn’t get to ride that cycle the way BULL or SOCI do. If tanker rates stay elevated next year, I’ll be watching SMDR fall behind, not just grow more slowly.
The US$528m in debt is real, and although most of it is vessel lease liabilities, the payment obligation doesn’t shrink just because utilisation falls. If container volumes or logistics rates soften, those lease payments keep coming due regardless.
SMDR’s stake in Patimban, held through its subsidiary PT Samudera Pelabuhan Indonesia, now sits at around 21 percent, after Africa Global Logistics and Toyota Tsusho came in as partners and injected capital. SMDR’s own annual report, which I read directly, shows that stake falling from 99.9 percent at the end of 2024 to that figure over the course of 2025. If Patimban turns out to be as good as I imagine, SMDR only gets a fifth of it.
And most importantly: cheap relative to cash is no guarantee the price moves. The market could simply be right, and SMDR could deserve a price this low for a reason I haven’t spotted yet, maybe something about governance, maybe about the quality of earnings given how large the non-controlling interest is (US$27.03m of US$79.08m total 2025 profit belongs to minority shareholders in its subsidiaries), or some other reason I haven’t found.
A note
I read two of SMDR’s own audited filings directly: the annual statements for 31 December 2025 and the interim statements for 30 June 2026, both downloaded from the company’s own site on 19 September 2026. From those I confirmed for myself: total profit for the year in 2025 was US$79,084,613, up only 2.7 percent from US$76,979,315, and the amount attributable to owners of the parent was US$52,050,752. The US$81.01m, +20.1 percent figure circulating under SMDR’s name on one news site doesn’t match the actual filing, so I haven’t used it.
The Rp17,745-per-dollar rate is Bank Indonesia’s JISDOR for 18 September 2026, the same rate used for another calculation on this blog dated that same day. Every market-cap conversion to dollars above is my own.
I deliberately didn’t use a sum-of-the-parts technique or state any fair-value number for SMDR. Not because the technique is wrong, but because every input available to calculate one here is still, to me, a guess, and the report I discarded at the top of this post is a live example of why that’s dangerous.
SMDR’s 52-week range differs between sources I found, Rp250 to Rp474 in one place and Rp192 to Rp474 in another, and I didn’t get to settle which is correct before publishing this.
This is about why I hold one stock. It isn’t an invitation to hold it too.