/10 min read
A YouTube title says ships are paying 40 times more to cross. The dollar figure behind it is real, the rupiah conversion is stale, and the comparison is against the wrong thing. What happens when ships take the long way round is the more interesting part.
When I introduced myself I said I like reading about geopolitics because it comes down to people deciding without complete information. My YouTube homepage handed me an example, and the joke is that this time the one short of information was me: the video is for members, and I’m not a member.
It runs 25 minutes and 10 seconds and I didn’t watch it. All I could examine was the title and the cover image.
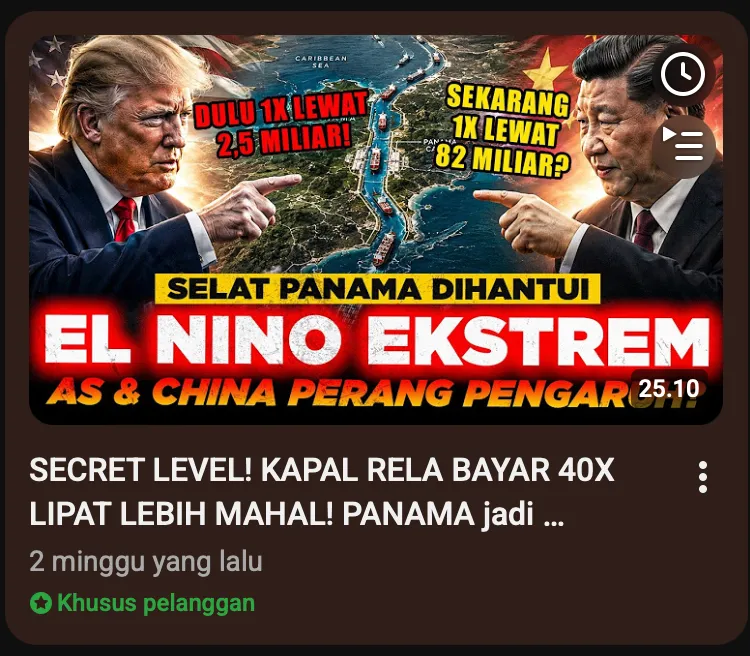
The cover that came past my homepage. The title promises a fortyfold rise; the image carries two rupiah figures, El Niño, and two heads of state.
The title says ships are willing to pay 40 times more. The image puts up two numbers: one crossing used to cost Rp2.5 billion, now one crossing costs Rp82 billion. The rest of it reads “the Panama Strait haunted by extreme El Niño” and “the US and China fight for influence.”
Those two rupiah figures don’t even produce 40 between them. Rp82 billion divided by Rp2.5 billion comes to about 33.
The dollar figure is right, the rupiah one is stale
In late August 2026 an LPG carrier called G. Spirit, operated by South Korea’s SK Gas, won a Panama Canal slot at auction for US$5.3 million for a single northbound crossing on 1 September. FreightWaves records it as the highest price ever reported, beating a US$4.6 million record set by the G. Arete earlier that same month.
So the event is real. It’s the conversion that slips. At the JISDOR reference rate published by Bank Indonesia, the central bank, on 18 September 2026 of Rp17,745 to the dollar:
5,300,000 × 17,745 = Rp94.0 billion
You only reach Rp82 billion if a dollar costs about Rp15,470, and that rate has been gone a long while. On this point the cover isn’t exaggerating. It is twelve billion rupiah short.
The other figure is harder to check. Rp2.5 billion at the same rate is roughly US$141,000, which is not far from the Neopanamax reservation fee FreightWaves puts at around US$100,000. I couldn’t find that number on the ACP’s own published tariff table, so I won’t treat it as settled.
Crossing the Panama Canal isn’t paid as one number
The published tariff notes from the ACP, the Panamanian government agency that runs the canal, set out three separate charges: tolls, which every vessel pays and which are calculated from its size and what it carries; a reservation fee, if the ship wants a guaranteed date; and an auction for slots not otherwise taken. My reading of that document is that the US$5.3 million is the third of those, sitting on top of the tolls rather than replacing them.
If that’s right, comparing it to “one crossing” will always be wrong, because there is no single price for one crossing. The only like-for-like comparison is other auctions, and FreightWaves has the number: the median auction price between October 2025 and February 2026 was around US$55,000.
5,300,000 / 55,000 = 96 times the median auction price
That calculation has a weakness of its own. October to February is the window before the drought peaked, so the median comes from a calmer stretch, and I couldn’t find a 2026 median to replace it with. But the direction is not in doubt: on the axis that actually works, the jump is far bigger than fortyfold, and the 40 in that video title is measured against the wrong axis.
Why anyone would pay it
The passage is still there. What the ACP auctions is the date.
As of 20 August 2026 the ACP counted 36 vessels queuing without a reservation, waiting an average of 8.5 days northbound and 7.7 days southbound. Eight and a half days is not only eight and a half days: the charter keeps running, the crew still gets paid, and the contract at the far end has a date on it.
But this is where I have to stop. I don’t know what SK Gas signed, what the cargo was worth, or what penalty was waiting if it arrived late. So whether US$5.3 million was a good decision, I can’t say.
All I can say is this: somebody had already seen every one of those numbers, and decided to pay.
The cause is water, not Trump and Xi
In Advisory to Shipping A-29-2026, dated 20 August 2026, the ACP reports rainfall across the canal watershed running 34 percent below average and inflows 44 percent below. The Panama Canal needs fresh water to lift and lower ships through each lock. Less water, so fewer ships: from 15 September, total daily transits were cut to 32, of which nine are Neopanamax slots.
The sequence is worth noticing. That advisory came out on 20 August and the US$5.3 million auction happened after it, for a 1 September sailing, while the cut to 32 transits only took effect a fortnight after that sailing. The record price was set not because the canal had already narrowed, but because everyone already knew it was going to.
And the loudest word on that cover turns out to be the best supported one, even though the formal confirmation arrived later. NOAA raised its status to an El Niño Advisory on 10 September 2026, putting the odds above 90 percent that this becomes a very strong event running into the 2026-27 winter. Australia’s Bureau of Meteorology recorded the Niño3.4 anomaly at +2.51 degrees in mid-September.
It’s the geopolitics that misses. The canal has been run by the Autoridad del Canal de Panamá, a Panamanian government agency, since the United States handed it over on 31 December 1999. China has never operated it.
What China did have a connection to is the two ports at either end, Balboa and Cristóbal, long held by CK Hutchison of Hong Kong. That story has already moved on. After Panama’s Supreme Court voided the concession on 30 January 2026, interim operations went to Maersk’s APM Terminals at Balboa and to MSC at Cristóbal. CK Hutchison is fighting back on two fronts at once: an ICC arbitration in its subsidiary’s name claiming at least US$2 billion, and, since August 2026, an investment treaty arbitration claiming more than US$1.5 billion, according to WorldCargo News.
So what narrowed the canal wasn’t Trump and it wasn’t Xi. It was rain that never came.
Ever Given taught the same lesson in six days
Five years ago there was a far faster version of this.
Ever Given grounded in the Suez Canal on 23 March 2021 and was refloated on 29 March, by the Suez Canal Authority’s own account. Six days, one ship 400 metres long carrying 20,124 containers, and by the time she came free 422 vessels were queuing, again the canal authority’s own figure. The backlog didn’t fully clear until 3 April.
The number most often quoted from that week is US$9.6 billion a day, from Lloyd’s List. It needs reading carefully: that is an estimate of the value of goods that normally pass through daily, and Lloyd’s List called it a rough calculation itself. The cargo was delayed, not destroyed.
The part nobody quotes is the useful one. A small number of ships decided not to wait and went around the Cape of Good Hope instead — Port Economics counts 27 of them in its academic reconstruction, and notes that going round added seven to ten days of sailing, roughly as long as the queue took to unwind. Its conclusion: the ships that went around and the ships that waited reached their destinations at about the same time.
That is the kind of bet now being placed at Panama, with two differences. Suez in 2021 was a total blockage that ended in six days. Panama in 2026 isn’t blocked, has no end date, and its slots carry a price.
Ships started going the long way round, and that is where the opportunity is
Going around sounds like the way out. For the industry it works the other way.
A ship sells two things at once, cargo space and time. The same cargo over a longer distance ties that ship up for longer doing the same job. Not one vessel leaves the fleet, and yet the fleet carries less.
The best measure of this comes from the container market rather than from LPG, which I should say plainly before carrying it across to Panama. The Asia-Europe route during the Red Sea diversions has the cleanest data. Between December 2023 and December 2024, Alphaliner recorded deployed capacity on that route rising 31 percent while the weekly capacity actually on offer rose only 8.8 percent. The gap is about twenty-two points, my own subtraction from those two figures, and it didn’t evaporate. Those ships were sailing around Africa.
From the same Alphaliner work: the detour absorbed 1.76 million TEU, or 59 percent of all the new container capacity delivered that year. The world container fleet grew 10.6 percent across 2024, and the year closed with just 0.6 percent of it idle.
Clarksons records the same pattern from the demand side: seaborne trade volume rose 2.4 percent in 2024 while tonne-miles rose a little over 6 percent. Demand grew three times faster than the cargo did, purely because the distance grew.
What ships consume moved too. Across 2024, bunker sales at Singapore set a record of 54.92 million tonnes while Rotterdam fell 1 percent, and Singapore broke its record again at 56.20 million tonnes in 2025 according to Ship & Bunker. Fuel demand didn’t simply rise, it relocated along the new route.
At Panama the shape is starting to show, though in a different market. In April 2026, Vortexa counted about 43 percent of US Gulf to Asia LPG voyages going via the Cape of Good Hope, the highest share since October 2016. That is an April figure; I couldn’t find a September equivalent, so it shouldn’t be read as today’s position.
One thing keeps me from getting carried away, and it is the part that matters most. A route that lengthens can shorten again. Suez traffic in the four weeks to 20 August 2026 was the highest since January 2024 according to Lloyd’s List Intelligence, though still 41 percent below pre-crisis levels. And Drewry, on 17 September 2026, explains softening Asia-Europe rates with the same cause: ships are going back through Suez.
So the thing worth watching isn’t the auction price that made the video title. That price is a symptom, and symptoms can disappear as fast as they arrive. The opportunity sits in the distance between two lines: how fast tonne-mile demand moves, and how fast the world’s fleet grows. While the first line stays above the second, shipowners are the ones who gain; once routes shorten while the newbuilds keep arriving, it runs the other way.
That is an observation rather than a recommendation, and I haven’t run the numbers on a single company yet.
El Niño tells us which way the first line is moving, not where it stops.
A note
I captured the title and cover from my own YouTube homepage on 19 September 2026. I didn’t watch the video, so nothing here judges its contents, only what is written in its title and on its image. The channel is Bennix.
The US$9.6 billion a day and the 27 ships that diverted during Ever Given are estimates, not official counts. The Ever Given compensation was never disclosed; the figure in circulation is around US$540 million, and that is reporting rather than confirmation.
A few numbers I came across didn’t make it in because I couldn’t find a source: a canal capacity said to be heading for 27 ships a day, and waiting times of 10 to 11 days. The waiting figure I used is 8.5 days, from the ACP as of 20 August 2026.
The Rp17,745 rate is Bank Indonesia’s JISDOR for 18 September 2026, and rates move daily. The Rp94 billion, the 96 times and the twenty-two point gap are my own calculations from the figures above. Several of the sources above are rolling pages whose contents keep being updated, so every figure is written with the date I read it.
One small thing. The image says “Selat Panama”, the Panama Strait. Panama has a canal, not a strait.